Welcome to RVForums.com

  • Register now and join the discussion
  • Friendliest RV Community on the web
  • Modern site for PC's, Phones, Tablets - no 3rd party apps required
  • Ask questions, help others, review campgrounds
  • Get the most out of the RV Lifestyle
  • Invite everyone to RVForums.com and let's have fun
  • Commercial/Vendors welcome

FYI 45 MPH rear end collision.

Welcome to our community

  • Register now and join the discussion
  • Modern secure site, no 3rd party apps required
  • Invite your friends and let's have fun
  • Commercial/Vendors welcome
  • Friendliest RV community on the web

dkolakowski10

RVF Regular
Joined
Sep 14, 2026
Messages
8
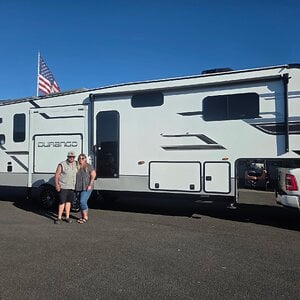
2024 Renegade Verona 40VRB.
07-12-2026 headed North on I-75 in Ocala.
A rainy day that turned ugly after passing under the FDOT LED sign with a message that said "prepare to stop 3 miles ahead".
After driving under an overpass I clearly saw all three lanes ahead were red brake lights and flashing blue FHP light bars.
I came off the fuel pedal and let the engine break do it's thing.
I was about to push the 4 way button and looked into the driver side mirror.
I couldn't believe my eyes and screamed hang on!
A commercial semi truck tanker was closing in fast and the road mist was unbelievable.
I heard an explosion and my head snapped backward and after that silence. I was strapped in and my chest and jaw hurt.
After all the confusion and over a month of insurance uncertainty, Freightliner and Renegade deemed my Verona a total loss.
The house was pushed forward by 6" and the cab separated from the house. The wheel wells were cut open to allow the Verona to be towed down the road.
We just settled with a commercial insurance company who paid what they considered the Verona value at the time of impact.
Let me tell everyone who has an RV and enjoys the freedom and comfort of driving down the road.
When an accident happens and it maybe your fault or the other drivers, it's the insurance company and policy that decide if you keep that dream alive.
With our situation we are grateful that the company had insurance because even after a settlement we are unable to become whole again.
The money exchange is way short of providing a replacement Super-C, and we are coming out of pocket in hopes of being placed into another Renegade.
Insurance companies do not provide a replacement for what was lost and they are up front about that!
Take what we offered and move on is the "buyer be ware" when you are driving down the road in a $365,000.00 RV today.
An accident even when it's the others person fault can change your dreams in an instant and you are left with minimal funds when the dust clears.

Moral of this story:
Renegade builds a very solid Super-C and I wouldn't own anything else!

Be safe out there!
 
I'm glad there were no serious injuries!!
If the other insurance carrier's valuation was too low, did you contest it?
 
Sorry to hear of this experience. Not sure if law suit is apprpriate here. Would not hurt to call one of the big guys from the TV commercials.
 
Glad everyone was safe overall. Safety of the M2 is one of the reasons we had a Super C.

That is why we had a negotiated value policy on ours. Basically would have got back what we paid had it been totaled.
 
I'm glad there were no serious injuries!!
If the other insurance carrier's valuation was too low, did you contest it?
The biggest problem is that there simply aren’t enough truly comparable vehicles on the market to establish an accurate value. The commercial insurance company relied on JD Power electronic data and two currently listed 2024 Renegade Verona 40VRBs. They also used a 2024 Renegade Verona 40VBH as a comparable, even though it does not have the same floor plan and typically carries an MSRP that is $5,000–$8,000 lower because it has only one bathroom.
I sent several emails requesting the detailed breakdowns and worksheets showing exactly how they arrived at their $316,000 valuation for my Verona. Unfortunately, those requests fell on deaf ears. They refused to provide the supporting calculations and would not even open a meaningful discussion regarding my counteroffer of $335,000—the amount I believe is necessary to replace the vehicle and put me as close as possible to where I was before the loss.

"NOT ASKING FOR MUCH CONSIDERING A COMMERCIAL DRIVER CLEARLY WAS NOT PAYING ATTENTION BEFORE IMPACT"!

What makes this even more frustrating is that I went a step further and provided examples of current 2026 Renegade Verona 40VRBs, which are substantially higher in price. I even went on a bit of a rant toward the end of my email correspondence and challenged them to produce a 2024 Renegade Verona 40VRB with fewer than 9,400 miles, a documented service history, and low generator hours for $316,000.

They couldn't—because that vehicle simply doesn't exist.
And that, in my opinion, makes the point even clearer. You cannot claim that $316,000 is a fair replacement value when you cannot actually find a comparable vehicle with similar age, mileage, condition, equipment, floor plan, service history, and generator hours for that amount.

Bottom Line:​

This experience has reinforced my belief that big insurance companies are primarily focused on collecting premiums and minimizing payouts. When it comes time to make a customer whole after a loss, the emphasis seems to shift from fair replacement value to finding the lowest number they can justify on paper. For me, this isn't about trying to make money on the loss. It's about being able to replace what I had with something genuinely comparable without having to absorb a significant financial loss simply because the insurance company's valuation doesn't reflect the actual market.

If $316,000 is truly the fair market replacement value, then finding a comparable 2024 Verona 40VRB under those criteria should be easy.

It isn't.

And that says a lot.

A final note: My wife and I have never been in a motor vehicle accident in both our 45 year average as insured drivers. If the other person would have followed the safety warning from FDOT and looked at the road and not a phone (allegedly) I wouldn't be a new member to this forum and probably would be in the Florida keys right now!
 
Glad everyone was safe overall. Safety of the M2 is one of the reasons we had a Super C.

That is why we had a negotiated value policy on ours. Basically would have got back what we paid had it been totaled.

A Note About the Insurance Rider​

We actually had a policy rider that addressed this situation as well. If I had caused the accident, I would have recovered the value we specifically stated on the policy. That amount still would not have completely made me whole, but it would have covered the overall loan payoff and then some.
Because the other driver was 100% at fault, however, the situation is different. The at-fault driver's insurance company is the one determining how the claim is valued and how the payout is handled.
And to be fair, I'm not saying their offer was necessarily unreasonable or ungenerous in the context of how they calculated it. My point is something different: insurance companies aren't necessarily interested in replacing your totaled RV at today's actual replacement cost. They determine what they believe the vehicle you lost was worth and offer that amount. The problem is that the number they determine may not be enough to actually put you back on the road in a comparable RV.
That's the part that is so frustrating.
The accident wasn't something I caused, yet I'm the one left facing the difference between what the insurance company says my RV was worth and what it actually costs to replace it with something comparable in today's market.
In other words, the at-fault driver took away a vehicle that I owned and had invested heavily in. The insurance settlement may compensate me for what they believe that vehicle was worth, but it doesn't necessarily provide enough money to replace what was actually taken away.

And if replacing that vehicle requires me to come out of pocket with tens of thousands of additional dollars, then am I really being made whole?

​

 
did you have uninsured/underinsured coverage? I would think that would kick in your negotiated price rider.
 
did you have uninsured/underinsured coverage? I would think that would kick in your negotiated price rider.
An insured person and the insurer have a legal contract together. In the event of a collision, as long as coverages exist, one should be only dealing with that company. One does not have a legal contract with a third party insurer. The insurer that agreed to a replacement price in the event of a loss is the one that undertook the risk. They would be the one's taking the loss if the third party insurer was able to confirm the Actual Cash Value of the iunsured unit was less than the agreed upon value. That is why the premium was charged.
 
The only accident we've had we only worked with our insurance, even though we were not at fault.
Our policy paid the claim exactly as it should have and then subrogated against the other party's insurance.
They returned our deductible several months later so they must have been able to collect from the other carrier.
Yep. That's how it works. It is far better to have an insurance company working for you than against you. I spent 54 years working in the collison repair industry either working for them, working against them and working with them.
 
Update:
We agreed to accept the GW insurance EVC of $316,000.00. The insurance company towed our Verona from the Freightliner dealer on 09-08-2026. The last we heard GW had to verify title and loan payoff, before a check was cleared and sent to us. That was 2 weeks ago and we have yet to hear anything from GW. Another monthly payment is coming due even though our Verona was totaled and we no longer have physical possession. We did receive the GW payment for PIP last week.
Overall, this has been extremely difficult and I'm still searching for a replacement Verona that will fill in the gap. My granddaughter keeps asking when is Papa going to get a new trailer and she hopes it's white because the last one was beautiful.
Stay safe out there and I can't wait to join everyone again soon!
 
Well as expected we agreed to the amount and signed away our Verona. The insurance company spent little time towing it to a place called CoPart where they will auction it off and someone will tear it apart. They towed the Super C Sept. 08 and we inquired about the pay off to our bank, because we had a payment due. CoPart never sent information to our bank requesting a loan payoff amount. We spent 4 weeks and talked to 6 different people trying to have anyone send paperwork to our bank. Chirp Chirp Chirp (crickets). Every person had an answer just not the correct answer and they all blamed my bank for not replying. My bank never received a document from CoPart so replying to thin air is kind of hard. Our last call and the agent who had a clue saw that they mis-filed our documents and they were never sent out for reply. Finally trumpets blare and our bank replied and the check is in the mail!
Morale of the story:
Big insurance will cut you down and strip you for every last cent associated to an accident in their favor. The clock ticks slowly when things go against them. They don't care to explain any of the reasoning behind how they determine a value. You just pay the premiums and keep their bank account fat so they have great bottom lines. They towed my vehicle and I continued to pay 2 months of premiums with interest before they ever had a title to that vehicle. It has taken 3 months to recover from an accident that wasn't my fault. I was subpoenaed to testify for the state against the commercial truck driver for excessive speed and failure to follow posted warnings. All this happened before I received a dime for my loss, pain and suffering. Both my shoulders still ache with pain if I rotate them or over extend. My wife's back is still giving her trouble and she uses pillows to support it while sitting on the couch. We decided to accept the accident and deal with these issues because after accidents happen. Honestly if this ever happens to me again I'll be that guy who calls a lawyer and heads to the hospital in a meat wagon. I've learned my lesson and frankly nice guys finish last.
 

Latest resources

Back
Top Bottom